
Office pods and UK capital allowances
For most UK businesses an office pod is deductible in full in the year you buy it. Because a FocusPod is freestanding and moveable rather than fixed to the building, it is normally treated as plant and machinery, which qualifies for the Annual Investment Allowance. This page explains how that works, with a worked example. It is general information rather than tax advice, so confirm your own position with your accountant.
Why a pod is plant, not building works
The line that matters for tax runs between alterations to the building and equipment used in the business. Partition walls, a built meeting room and the services that go with them become part of the premises, and much of that spend is relieved slowly through the structures and buildings allowance at a few per cent a year. Plant and machinery is different: it can attract full relief in the year of purchase.
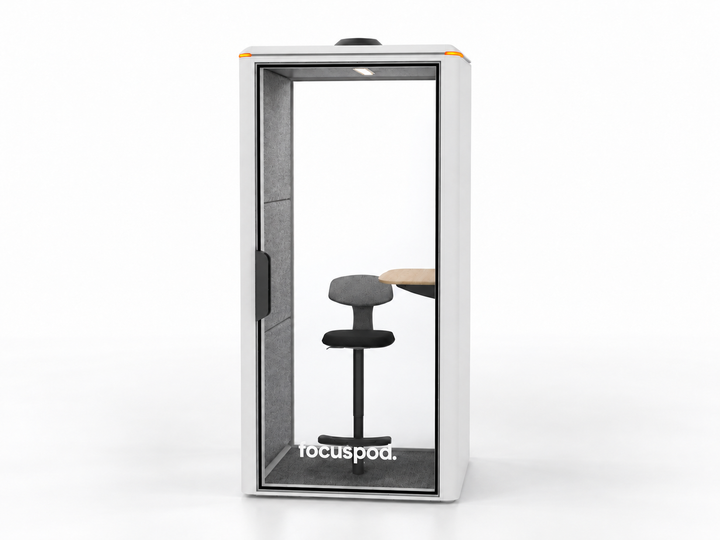
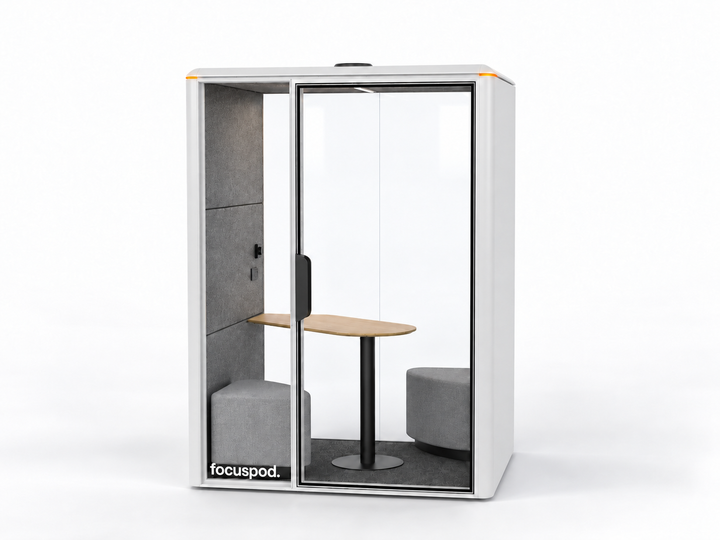
A FocusPod sits on the floor. It is not fixed to the building fabric, it needs no building control approval, it runs from a standard socket, and it is designed to be taken apart and moved when you relocate. Those are the practical characteristics of moveable plant rather than construction.
That difference is worth real money. The same budget solves the same problem either way, but the pod route can reduce this year's corporation tax bill in full, while the built room gives the relief back slowly over decades.
The two routes to full first-year relief
| Annual Investment Allowance | Full expensing | |
|---|---|---|
| Who can use it | Companies, sole traders and partnerships | Limited companies only |
| Annual cap | £1 million of qualifying spend | No monetary cap |
| Condition of the asset | New or second-hand | New and unused only |
| Relief | 100% in the year of purchase | 100% in the year of purchase |
For a pod project the practical difference is usually academic. Almost no business spends £1 million a year on equipment, so the Annual Investment Allowance covers the purchase either way.
A worked example
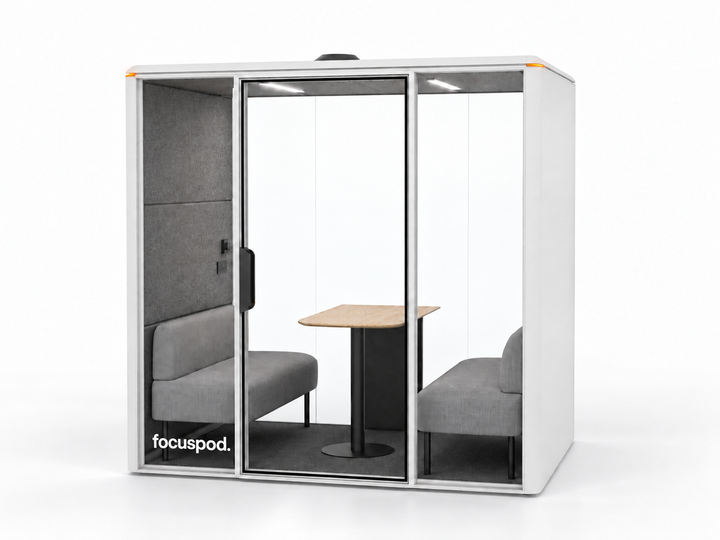
Take a profitable limited company buying a FocusPod Meet, the four-person meeting pod, with installation. The pod is £10,495 and installation is £1,395, so the qualifying spend is £11,890 excluding VAT.
| Line | Main rate (25%) | Small profits rate (19%) |
|---|---|---|
| Qualifying spend, claimed in full | £11,890 | £11,890 |
| Corporation tax saved | about £2,972 | about £2,259 |
| Effective cost of the pod | about £8,917 | about £9,630 |
If your business is VAT registered you would normally recover the VAT on top, in the usual way. The claim goes through your corporation tax return for the accounting period in which you buy the pod, so keep the invoice with your records.
Price the pod you actually want
Every FocusPod has a glass front and rear, built-in wheels and adjustable levelling feet.
Three things to get right
Timing. Relief lands in the accounting period in which you buy. A pod ordered before your year end reduces this year's bill; a week later and it becomes next year's. If a year end is approaching, tell us and we will be straight with you about whether the delivery window supports it.
Business use. The pod needs to be for the business. A pod installed at a director's home and used privately raises benefit-in-kind questions, so take advice before going down that route.
Clean invoicing. If a pod is bought inside a larger fit-out contract, make sure it is itemised separately so the plant treatment is obvious. Our quotations list the pod, delivery and installation as separate lines for exactly this reason.
Common questions
Is an office pod plant and machinery or part of the building?
A freestanding pod that is not fixed to the building fabric and can be moved is normally treated as plant and machinery. A built partition room becomes part of the premises. That distinction is what drives how quickly the relief comes back to you, and your accountant will confirm the treatment for your specific facts.
What about garden office pods at home?
Different rules, and a common source of confusion. Most content online about office pods and tax is really about garden buildings, where the structure itself usually does not qualify because it is a building. This page is about freestanding indoor pods bought by a business for its own premises, which is a much cleaner case.
Is VAT recoverable?
For a VAT-registered business buying a pod for business use, VAT is generally recoverable in the normal way. Our prices are shown excluding VAT, as is standard for business purchases.
Does the relief still work for several pods?
Yes. The Annual Investment Allowance covers up to £1 million of qualifying spend a year, so multi-pod projects sit comfortably inside it. Each pod is itemised on the quotation, which keeps the claim straightforward.
What if we lease or finance the pod?
The treatment depends on the structure of the agreement, and it is one of the first things to check with your accountant. Tell us what you are considering and we will make sure the paperwork matches it.
Ask for it itemised
Build the configuration you want, then ask for the quotation itemised the way your accountant prefers: pod, delivery and installation as separate lines, with the VAT shown separately.
This page is general information for UK businesses and is not tax, accounting or financial advice. Allowances, rates and thresholds change at fiscal events. Confirm the current position with your accountant or tax adviser before relying on any figure here.